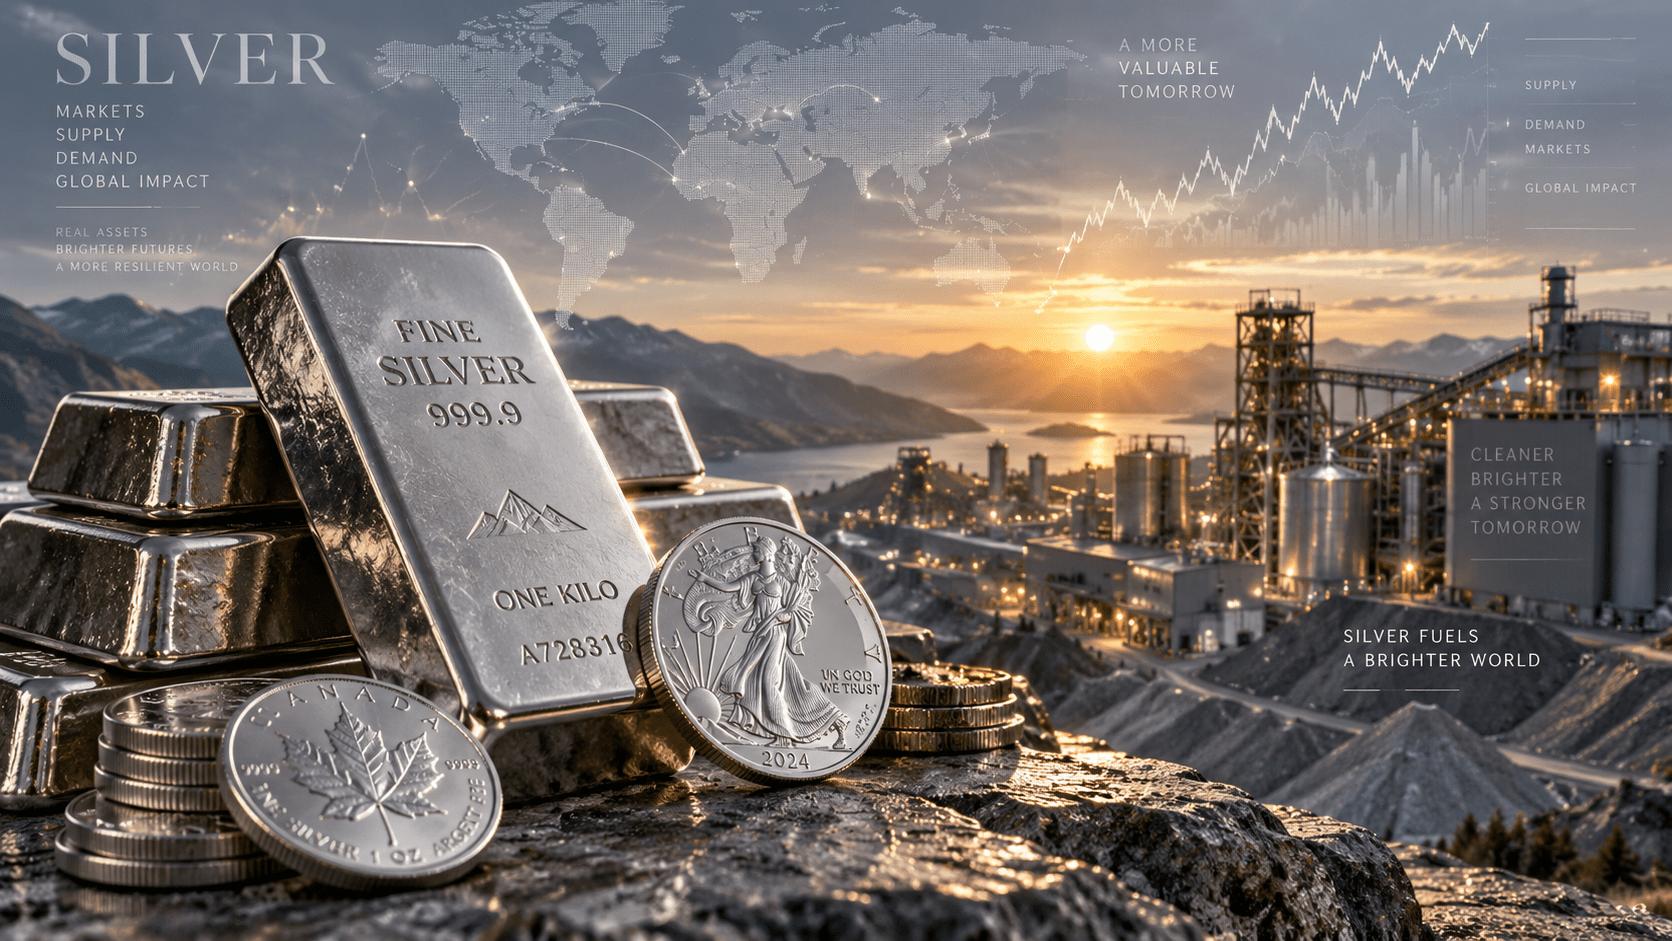
Silver is back above $65 an ounce after another volatile session on Thursday, September 17, but the current market is far more complicated than a simple precious-metals rally. Silver futures rose roughly 1.8% to settle around $65.47 and later traded above $66 during the session as Treasury yields retreated, oil prices eased and the U.S. dollar gave back some of the surge that followed Wednesday’s Federal Reserve rate hike. Earlier in the day, however, silver had traded lower, showing just how violently the metal is reacting to changes in interest-rate expectations.
That volatility comes after an extraordinary year. Silver was around $64.31 early Thursday, roughly 54% above its level one year ago, yet dramatically below the record above $121 reached in January. The collapse from that peak has removed some of the speculative excess from the market, but it has not eliminated the forces that drove silver higher in the first place. The global silver market is still expected to record a sixth consecutive annual supply deficit in 2026, physical investment demand is recovering, AI and data-center infrastructure are creating new industrial uses, and above-ground inventories remain an important source of metal needed to close the gap between supply and demand.
Silver therefore enters the final months of 2026 caught between two very powerful forces. The macro environment has become increasingly hostile as central banks fight another inflation shock with higher rates, while the physical silver market remains structurally tight. Which force wins will likely determine whether the current $60s become a base for another rally or merely a pause before a deeper correction.
The Fed Just Delivered Exactly the Kind of News Silver Usually Hates
The biggest short-term pressure on silver comes from monetary policy. On September 16, the Federal Reserve raised its benchmark interest rate by 25 basis points to a range of 3.75% to 4.00%, its first hike in more than three years. Sixteen of 18 policymakers indicated that at least one additional increase could be appropriate before the end of 2026, while markets continue to price even more tightening than the Fed itself currently projects.
That is normally bad news for silver. Like gold, bullion produces no yield, so higher interest rates increase the opportunity cost of holding it. A stronger dollar creates another headwind because silver becomes more expensive for buyers using other currencies. Those pressures were visible immediately after the Fed decision, when the dollar jumped and short-term Treasury yields climbed.
Related articles

Yet Thursday produced an important counter-move. Long-term Treasury yields eased, the dollar softened slightly and oil prices fell, allowing both gold and silver to rebound. Silver’s jump of roughly 2% showed how quickly the metal can recover when macro pressure eases, even if the underlying Fed stance remains hawkish.
That makes interest rates the first major variable silver investors need to watch. The market does not necessarily need the Fed to cut rates for silver to rally. It may only need investors to conclude that the tightening cycle will be less aggressive than feared. If yields retreat and the dollar weakens, silver’s structural supply story can return to the foreground very quickly.
Silver Is Still Living With the Aftermath of a $121 Mania
The current price around the mid-$60s looks very different when placed against what happened earlier this year. According to the Silver Institute, silver surged above $121 an ounce on January 29 before falling sharply back toward the $70s by early April. The extraordinary move followed a powerful 2025 rally characterized by tight physical liquidity, large investment flows and repeated market deficits.
That January spike was not sustainable. Silver’s smaller market makes it far more volatile than gold, and investment flows can push prices dramatically in either direction when available physical liquidity becomes tight. As prices moved above $100, substitution and recycling incentives increased while speculative demand became more vulnerable to any shift in interest rates or the dollar.
The subsequent decline into the $60s therefore should not automatically be read as the end of the bull thesis. It also represents a significant repricing from extreme levels. Silver is still trading well above where it stood one year ago, but expectations are considerably less euphoric than they were during the January squeeze.
That matters because the fundamental market remains in deficit even after high prices have begun destroying some demand.
The Silver Market Is Heading for a Sixth Straight Supply Deficit
The clearest long-term support underneath silver comes from the physical market. The Silver Institute expects total global silver supply to reach roughly 1.05 billion ounces in 2026, while the market remains in deficit for the sixth consecutive year. Its February forecast put that deficit at approximately 67 million ounces, while the later World Silver Survey estimated a 2026 shortfall around 46 million ounces under updated assumptions.
The exact number matters less than the direction. For several years, demand has exceeded newly available supply, forcing the market to rely on above-ground inventories. The cumulative deficit has already removed hundreds of millions of ounces from available stocks, tightening the physical market and making it more sensitive to investment flows.
Supply is difficult to increase rapidly because most silver is produced as a by-product of mining other metals such as lead, zinc, copper and gold. That means miners cannot necessarily respond to higher silver prices by simply doubling silver production. The Silver Institute expects mine output to increase only modestly this year, while recycling rises as consumers take advantage of high prices.
That structural constraint is one reason silver can behave differently from many other commodities. Rising prices eventually attract more recycling and reduce some consumption, but new mine supply responds relatively slowly.
AI Is Replacing Solar as the More Interesting Industrial Story
Silver’s industrial-demand picture is changing, and this is one of the most important parts of the current market.
For years, photovoltaics were one of the dominant growth stories because solar panels use silver paste in electrical contacts. But silver’s own success has encouraged manufacturers to use less of the metal per panel or substitute alternative materials wherever possible. The Silver Institute now expects industrial silver fabrication to decline in 2026, largely because of reduced photovoltaic consumption despite continued growth in global solar installations.
That would normally sound bearish.
But another group of industries is beginning to offset part of the decline. Data centers, AI hardware, automotive electronics, power-grid investment and aerospace all require silver because of its exceptional electrical conductivity. The Silver Institute specifically identifies AI-related technologies and data-center expansion as structural sources of silver consumption.
This matters because AI infrastructure is still in the middle of an enormous investment cycle. Data centers require servers, switches, power electronics, cooling systems, backup infrastructure and grid upgrades, all of which contain electrical components where silver can be used. The individual quantities may appear small, but multiplied across hyperscale infrastructure, the demand becomes meaningful.
Silver therefore has an unusual dual exposure to the AI boom. Semiconductor and technology stocks capture the revenue side of the buildout, while silver can benefit from the physical electrical infrastructure required to support it.
Investment Demand May Be More Important Than Industry Right Now
Industrial demand attracts much of the attention around silver, but investment flows can move the price far faster.
The Silver Institute expects physical investment demand to rise roughly 20% in 2026 to a three-year high of 227 million ounces as buyers return to bars and coins. Global exchange-traded product holdings have also remained substantial after large inflows during 2024 and 2025.
That demand can become especially powerful when investors are worried about inflation, currency stability, sovereign debt or geopolitical risk. The current environment contains all four. Oil remains above $100 despite easing from recent peaks, global inflation is again creating concern, and major central banks are being forced toward tighter policy even as growth risks increase. Reuters described the current setup as an emerging stagflation problem in which high energy costs collide with rising rates and weaker consumer purchasing power.
Silver benefits from that uncertainty because it trades partly as a monetary metal, but there is an important complication: inflation can help silver only until it pushes interest rates too high. That is the tension dominating the market right now.
High inflation supports the argument for hard assets.
High real yields undermine it.
Silver’s Relationship With Gold Is Becoming Crucial Again
Silver often behaves like a leveraged version of gold. Both respond to the dollar, interest rates and safe-haven demand, but silver’s smaller market and industrial exposure typically produce much larger percentage moves.
That relationship was visible again Thursday. Gold gained more than 2% as the dollar and Treasury yields eased, while silver rose even more aggressively later in the session.
The Silver Institute’s 2026 survey shows that silver’s correlation with gold has remained high, even as its relationship with industrial metals has also strengthened during periods of strong economic demand.
That dual identity can be powerful in a bullish environment. If gold rises because monetary conditions ease while industrial demand remains strong, silver receives support from both sides of its market.
But the same structure becomes painful when the signals diverge. A recession can hurt industrial demand even while helping gold. A strong economy can support industrial silver consumption while pushing rates higher and hurting precious metals. Silver therefore rarely provides the clean macroeconomic exposure that gold does.
That complexity is also why the moves can become so dramatic.
Silver Price Forecast: $60, $70 and the Battle in Between
The current mid-$60s area has become an important battleground after months of extreme volatility.
The bearish scenario begins with renewed dollar strength and rising Treasury yields. If oil resumes its advance, inflation remains stubborn and markets become convinced that the Fed will deliver several additional rate hikes, silver could struggle to hold the low-$60s. A decisive break lower would likely revive concerns that the post-January correction still has further to run.
The more neutral scenario is consolidation between roughly $60 and $70 while investors wait for clearer evidence on inflation and monetary policy. That environment would allow the physical deficit and investment demand to provide support without removing the macro pressure created by elevated rates.
The bullish scenario requires the dollar and yields to retreat while physical tightness remains intact. A sustained move through $70 could shift attention back toward the powerful structural drivers that produced the earlier rally. Silver’s history this year has already demonstrated that once investment flows accelerate in a tight physical market, price moves can become unusually fast.
The January record above $121 should not be treated as an obvious near-term target simply because it existed earlier this year. That level reflected an exceptional combination of liquidity pressure, momentum and investment demand. The more important question is whether the current market can establish a durable base after giving back nearly half of that extreme move.
Silver’s Bull Case Is Still Alive — but It Is No Longer Easy
The current silver market may actually be healthier than it was near January’s record because the speculative excess has been dramatically reduced while the structural deficit remains.
Silver is still roughly 54% above its year-ago level. The market is expected to remain undersupplied for a sixth consecutive year. Physical investment demand is strengthening, and new industrial uses tied to AI, data centers, vehicles and power infrastructure continue expanding even as solar manufacturers use less silver per panel.
But investors are also confronting an aggressively different interest-rate environment. The Federal Reserve has resumed hiking, policymakers expect additional tightening, and the dollar can strengthen quickly whenever inflation fears intensify. Those factors could keep silver volatile even if the physical market stays tight.
That leaves silver in an unusually balanced position.
The long-term supply story remains constructive.
The short-term macro story remains dangerous.
If Treasury yields continue retreating after this week’s Fed decision and the dollar loses momentum, silver could once again begin trading primarily on scarcity and investment demand. If inflation forces the Fed into a much more aggressive hiking cycle, however, the metal may need to absorb more monetary-policy pressure before the physical deficit becomes dominant again.
Silver has already traveled from below $50 to above $120 and back into the $60s within an extraordinary period of volatility.
The next major move will likely depend on which side of its identity wins first: silver the precious metal, fighting higher interest rates, or silver the scarce industrial commodity that the global economy keeps consuming faster than it can comfortably replace.
Disclaimer
This article is for informational purposes only and does not constitute financial or investment advice. Readers should conduct their own research and, where appropriate, consult a qualified financial advisor before making investment decisions. This article was researched and drafted with the support of AI, then reviewed, fact-checked and edited by the editorial team before publication.