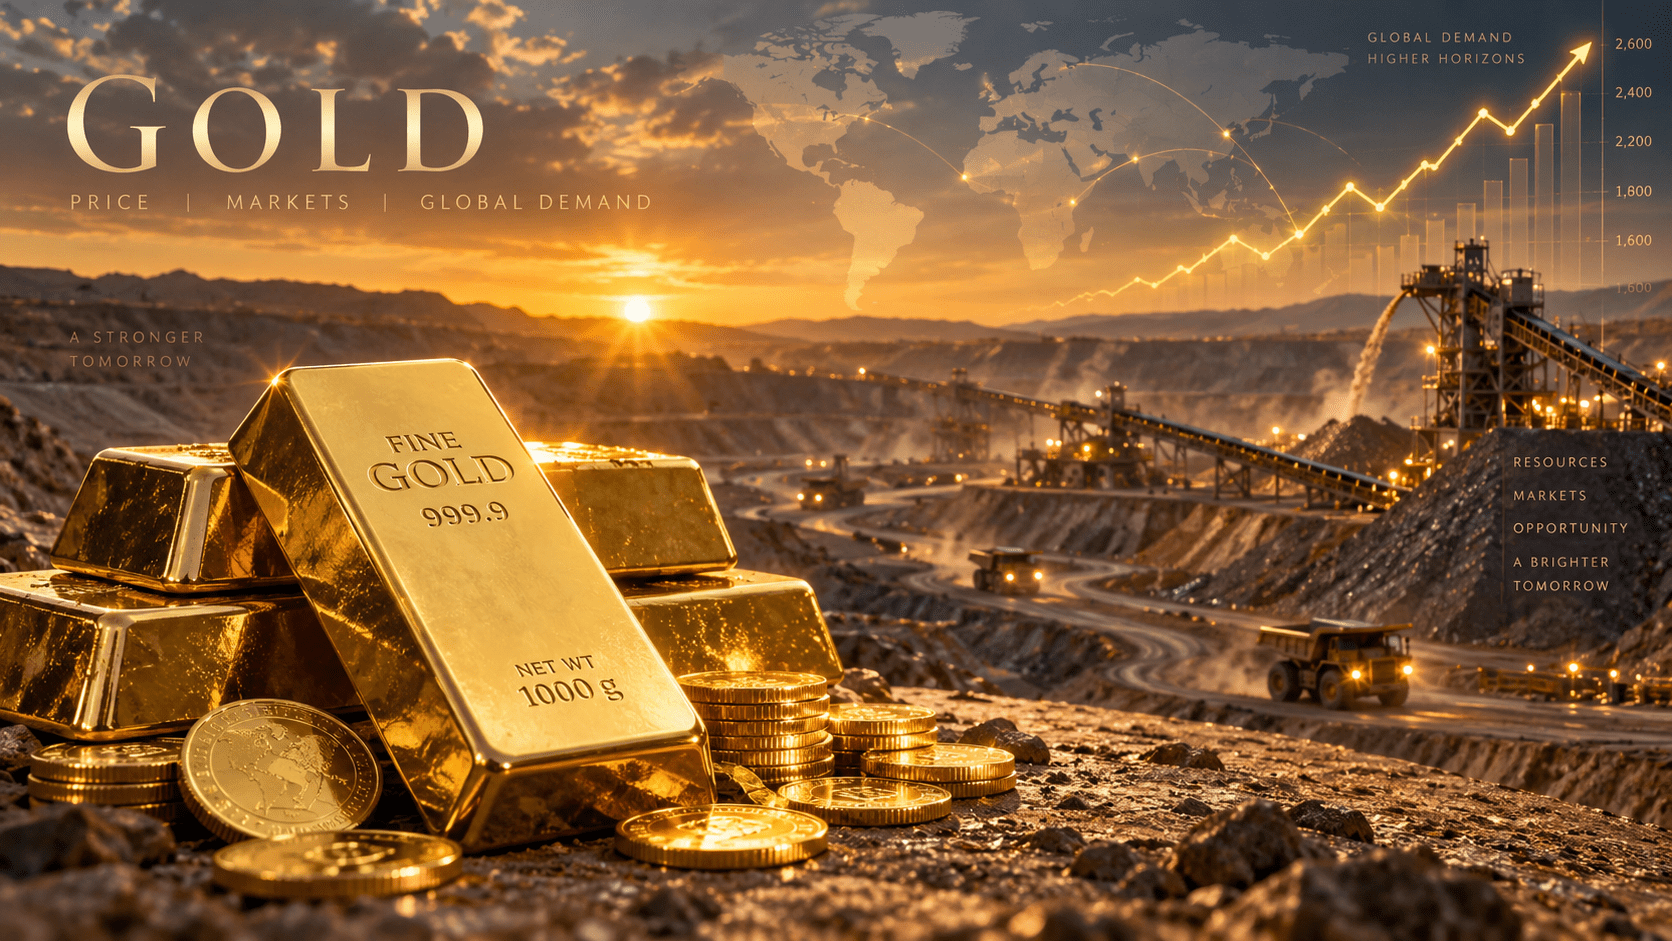
Gold is back under pressure on Wednesday, October 7, with the precious metal falling nearly 1% to around $4,123 an ounce during European trading as a stronger U.S. dollar and another surge in Treasury yields overwhelmed safe-haven demand. December U.S. gold futures dropped roughly 0.9% toward $4,149, reversing part of Tuesday’s 0.7% rebound and putting the gold price forecast 2026 back at the center of a battle between two increasingly powerful forces: investors worried about inflation, geopolitical instability and government debt, and a bond market offering yields high enough to make holding a non-interest-bearing asset considerably less attractive.
The timing is particularly important because today’s decline comes just hours before the Federal Reserve releases minutes from its September policy meeting. Markets have dramatically reduced expectations for another rate increase in October, but traders still see a strong possibility that the Fed could tighten again before the end of the year. That leaves gold trapped in an uncomfortable position. The long-term reasons investors have been buying bullion have hardly disappeared, yet the short-term mathematics of a stronger dollar and U.S. 10-year Treasury yields above 5.3% are suddenly working against it.
The result is a market that looks weaker on the screen today than it does underneath the surface.
And that distinction could determine whether the current pullback becomes the beginning of a deeper correction—or another opportunity for buyers waiting below $4,100.
Drop Today Has One Obvious Culprit: The Dollar Is Fighting Back
The immediate explanation for Wednesday’s decline is straightforward. The U.S. dollar index strengthened roughly 0.4%, making dollar-denominated gold more expensive for buyers using other currencies. At the same time, Treasury yields moved higher, with the benchmark 10-year yield climbing above 5.3%.
Related articles

That combination is particularly difficult for gold.
Bullion produces no interest, so investors holding it must accept an opportunity cost compared with Treasury securities. When government bonds yield more than 5%, that cost becomes increasingly difficult to ignore. A stronger dollar creates a second headwind because international investors effectively have to pay more in their own currencies to acquire the same ounce of gold.
The speed of today’s reversal makes the relationship particularly clear. Gold rose approximately 0.7% Tuesday to around $4,168 an ounce as Treasury yields temporarily eased and the dollar weakened. Less than 24 hours later, those two markets reversed direction—and gold followed them lower.
That tells investors something important about the current gold market.
The metal is still highly sensitive to interest rates.
Despite geopolitical conflict, fiscal concerns and continued central-bank buying, day-to-day price action is increasingly being dictated by the bond market. Until Treasury yields stabilize, gold bulls may have difficulty regaining the momentum that drove prices dramatically higher earlier in 2026.
But the Fed could change that equation.
Tonight’s Fed Minutes Could Decide Whether $4,100 Holds
The Federal Reserve’s September meeting minutes are Wednesday’s biggest scheduled catalyst for gold because investors are searching for clues about how aggressively policymakers may continue fighting inflation.
The Fed raised interest rates at its September meeting, and officials remain divided over how much additional tightening is necessary. Markets currently assign only around a 20% probability to another hike in October, but expectations for December are much more aggressive, with traders pricing roughly an 85%-86% probability of another increase before year-end.
That distinction explains why gold has not rallied more strongly despite fading expectations for an immediate October move.
The market isn’t asking only whether the Fed hikes this month.
It is asking whether interest rates will remain painfully high for longer.
Recent comments from Federal Reserve officials have kept that possibility alive. Kansas City Fed President Jeff Schmid and San Francisco Fed President Mary Daly have emphasized continuing inflation risks, reinforcing the idea that policymakers cannot simply declare victory because some economic indicators are cooling.
Oil is making that decision even more difficult.
Brent crude remains around $100-$102 per barrel amid continuing Middle East tensions, and expensive energy threatens to feed back into transportation costs, consumer prices and inflation expectations. If policymakers conclude that higher oil prices are preventing inflation from returning sustainably toward target, the Fed could remain restrictive longer than gold bulls expect.
That would keep real and nominal yields elevated.
For gold, that is the immediate danger.
The Bond Market Is Becoming Gold’s Most Dangerous Competitor
The pressure from Treasuries goes beyond another routine increase in yields. Long-duration U.S. government bonds are experiencing a historically significant selloff.
The 30-year Treasury yield climbed to roughly 5.70% on Wednesday, its highest level since 2002, while the 10-year yield moved toward 5.33%. Investors are demanding substantially more compensation to lend money to the U.S. government amid concerns about inflation, enormous fiscal deficits and the supply of new Treasury debt.
That creates an unusual conflict inside the gold thesis.
Government debt concerns can be bullish for gold because they encourage investors to seek assets outside the traditional fiat and sovereign-debt system. But when those same concerns cause Treasury yields to soar, bonds become more attractive relative to gold in the short term.
Gold is therefore being pulled in opposite directions by the same underlying problem.
Concerns about debt support the long-term case for owning hard assets.
The resulting bond selloff hurts gold today.
This contradiction helps explain why the metal can remain structurally bullish while still suffering sharp corrections. The longer Treasury yields remain around 5% or higher, the more difficult it becomes for speculative investors to justify holding gold purely on momentum.
Yet something important is preventing the market from collapsing.
There are buyers whose decisions are not based primarily on Treasury yields.
China Has Now Bought Gold for 23 Consecutive Months
Central banks remain one of the strongest structural supports underneath the gold market, and China continues to send a particularly clear signal.
The People’s Bank of China increased its gold holdings again in September, marking the 23rd consecutive month of purchases.
That buying matters because central banks operate differently from hedge funds or retail investors. They are generally not trying to capture a short-term move from $4,100 to $4,300. Gold is held as a reserve asset, providing diversification away from currencies and sovereign debt while carrying no direct counterparty risk.
That strategic motivation has become increasingly important in a world characterized by sanctions, geopolitical fragmentation and enormous government borrowing requirements.
For China and other reserve managers, the question may therefore be less about whether gold yields 0% while Treasuries yield more than 5% and more about whether reserve portfolios should remain overwhelmingly exposed to dollar-denominated assets.
That demand can provide a powerful floor beneath corrections.
It does not prevent gold from falling.
But it can change what happens when it does.
Middle East Tensions Are Creating a Strange Problem for Gold
Normally, geopolitical conflict is straightforwardly bullish for gold. Investors become nervous, capital moves toward perceived safe havens and bullion benefits.
The current Middle East conflict is more complicated.
Oil prices around $100 per barrel create geopolitical fear that supports gold, but expensive energy also increases inflation risks. Higher inflation can force the Federal Reserve to maintain higher interest rates, pushing Treasury yields upward and strengthening the dollar.
That can hurt gold.
Wednesday illustrates the contradiction. Middle East tensions remain severe, with attacks and threats to regional energy infrastructure keeping crude prices elevated. A developing storm in the Gulf of Mexico is adding another potential supply risk. Yet instead of surging on safe-haven demand, gold is falling because investors are focusing more heavily on the monetary-policy consequences of expensive energy.
The relationship therefore looks something like this: geopolitical tension pushes oil higher; higher oil increases inflation fears; inflation fears lift bond yields and support the dollar; and higher yields then pressure gold.
That chain can overwhelm gold’s traditional safe-haven response, at least temporarily.
It also means the next major move may depend less on geopolitical headlines themselves than on what those headlines do to inflation expectations.
$4,000 Is Emerging as the Level Gold Bulls Cannot Afford to Lose
Today’s decline toward $4,120 puts the market back within striking distance of a psychologically important area.
Analysts increasingly view approximately $4,000 an ounce as a major support zone where longer-term investors could return if the fundamental backdrop remains intact. Gold has recently been trading broadly inside the $4,100-$4,200 area, and the current correction has not yet destroyed the larger structural bull case.
That does not mean $4,000 is guaranteed to hold.
A surprisingly hawkish set of Fed minutes, another sharp move higher in Treasury yields or renewed dollar strength could accelerate selling. If gold decisively breaks below $4,000, momentum traders could amplify the decline and force the market to search for a lower equilibrium.
But a successful defense of the area would tell a very different story.
If gold repeatedly attracts buyers as it approaches $4,000 despite Treasury yields above 5%, it would suggest structural demand from central banks, long-term investors and geopolitical hedging remains powerful enough to absorb one of the most hostile interest-rate environments bullion has faced in years.
That would be a significant bullish signal.
And the industry’s own expectations remain surprisingly aggressive.
The Gold Industry Is Already Talking About $5,000
Delegates attending the London Bullion Market Association’s annual conference this week forecast that gold could reach approximately $5,013 an ounce over the next 12 months.
That forecast should not be treated as a guaranteed price target. Commodity markets can reverse violently, and industry participants naturally operate inside a sector that benefits from stronger precious-metal prices.
But the number illustrates how dramatically expectations have changed.
Gold above $4,000 would once have sounded extreme. Now industry participants are discussing another roughly $900 of potential upside while the metal trades around $4,100.
For that scenario to become plausible, several things probably need to happen.
Treasury yields would have to stabilize or retreat. The Federal Reserve would eventually need to signal that its tightening cycle is ending. Central-bank demand would need to remain strong, while geopolitical and fiscal concerns continue encouraging diversification into hard assets.
A weaker dollar would accelerate the move.
Conversely, persistent 5%-plus Treasury yields combined with further Fed tightening could delay the bullish scenario substantially.
That makes today’s selloff less a verdict on gold than a test of which macro force dominates next.
The Gold Price Forecast 2026 Now Comes Down to Rates Versus Fear
Gold’s nearly 1% decline on Wednesday looks dramatic after Tuesday’s rebound, but the move makes considerably more sense when viewed through the dollar and Treasury markets.
The dollar is stronger. The 10-year Treasury yield is above 5.3%. The 30-year yield has reached a 24-year high. The Federal Reserve is still discussing inflation while oil remains near $100 per barrel. For a non-yielding asset, that is a brutal combination.
And yet gold remains above $4,100.
That may be the most interesting number of all.
China has purchased gold for 23 consecutive months. Geopolitical tensions remain intense. Government debt concerns have not disappeared. Central banks continue diversifying reserves, and the gold industry itself sees the possibility of prices moving beyond $5,000 over the coming year.
The short-term gold price forecast therefore hinges on the Fed.
If Wednesday’s minutes reinforce expectations for another December rate increase and Treasury yields push even higher, $4,100 could give way and the market may quickly begin testing whether buyers really are waiting around $4,000.
If the minutes reveal greater concern about overtightening—or if bond yields begin retreating—the pressure currently holding gold down could reverse quickly. Tuesday already demonstrated how rapidly bullion responds when the dollar and yields move in its favor.
The broader bull market has not necessarily been broken.
It is being tested.
For investors, that makes the next few sessions far more important than today’s red percentage sign. The question isn’t simply whether gold loses another $30 or $50 from here. It is whether the market can absorb historically high Treasury yields without surrendering the $4,000 region that increasingly separates an ordinary correction from something much more serious.
Gold has spent 2026 proving that investors are willing to pay extraordinary prices for protection against inflation, debt and geopolitical instability.
Now the market is discovering exactly how much that protection is worth when supposedly risk-free U.S. government bonds are paying more than 5%.
Disclaimer
This article is for informational purposes only and does not constitute financial or investment advice. Readers should conduct their own research and, where appropriate, consult a qualified financial advisor before making investment decisions. This article was researched and drafted with the support of AI, then reviewed, fact-checked, and edited by the editorial team before publication.